Evidence before opinion
We compare sales and installation records with lender, surveyor, roof and financial evidence.
Analytics cookies
We use Microsoft Clarity to understand page performance. You can accept or reject analytics cookies. Privacy policy
Spray Foam assessment support
If spray foam insulation is affecting a mortgage, remortgage, equity release, property sale, survey or roof, the first step is to organise what was installed, what you were told, what the property evidence now shows and what financial impact has actually occurred.
Create a structured Spray Foam Insulation Assessment Report to bring the installation, mortgage, survey, finance, removal and complaint evidence together.
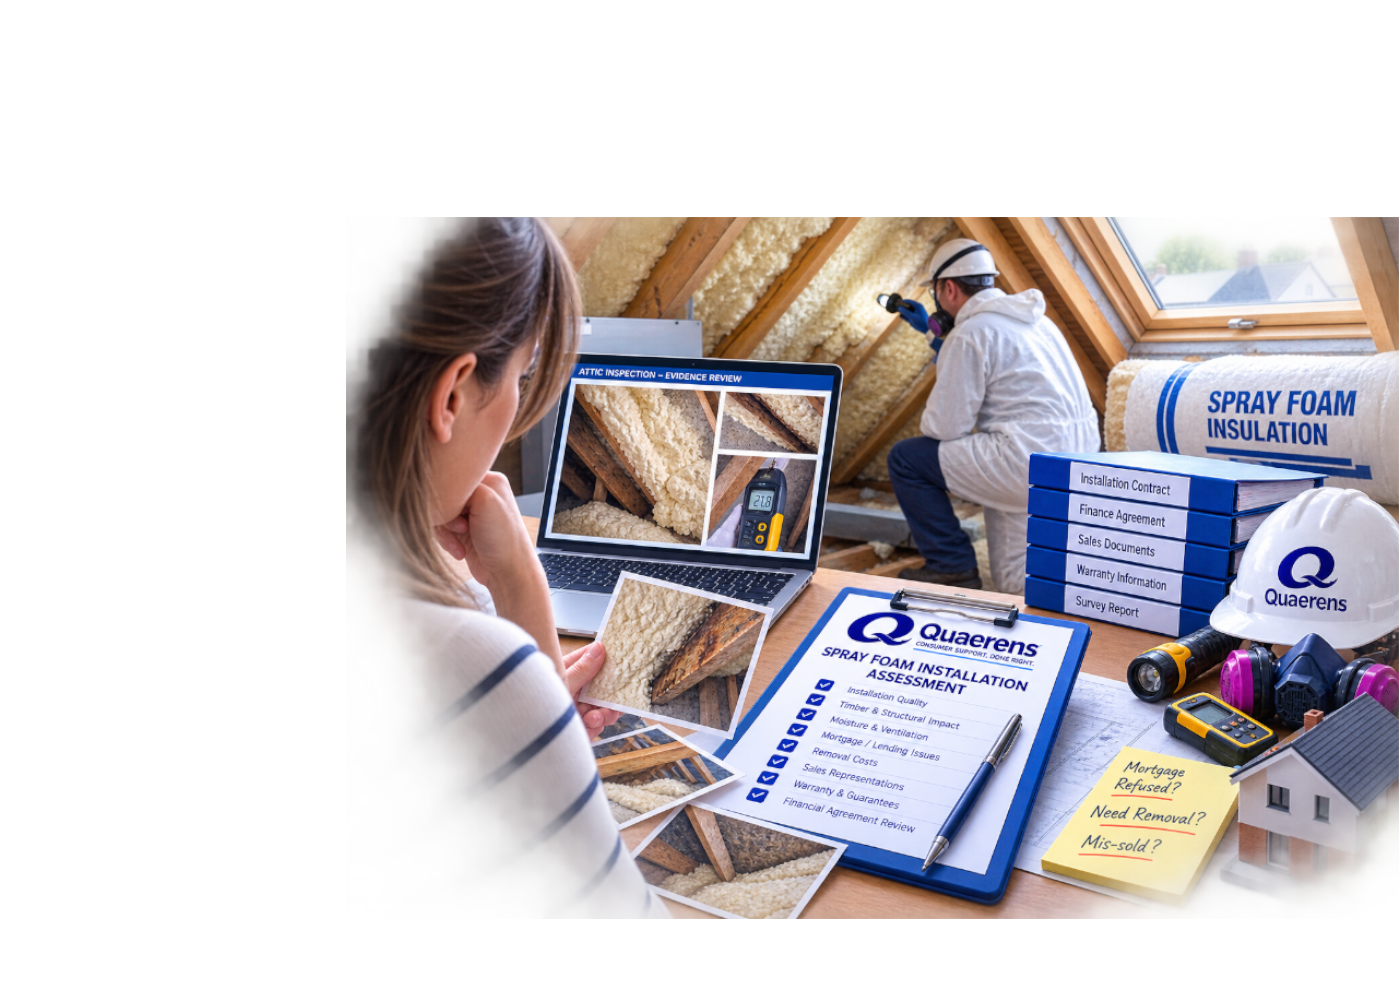
We compare sales and installation records with lender, surveyor, roof and financial evidence.
A lender concern or technical issue must be considered against the evidence for the actual property.
Quaerens provides structured assessment, evidence organisation and complaint support.
The report does not guarantee compensation, mortgage acceptance or recovery.
What the assessment can examine
A structured assessment helps distinguish consumer-reported information from documentary and professional evidence, while identifying what still needs verification.
Installer, date, product type, roof construction, membrane, rafters, ventilation, photographs, certification and guarantee.
Mortgage, resale, property value, energy, damp, roof, grant and government-backing statements, recorded according to the evidence available.
Lender or broker responses, valuation, surveyor concerns, equity release, buyer withdrawal, sale delay and written conditions.
Timber visibility, ventilation, moisture, condensation, membrane, rafters and any professional repair or replacement findings.
Why removal was suggested, who recommended it, quotes, scope, completion, reinspection, reinstatement and roof work.
Cash, card, finance, linked credit, grant or mixed funding, including complaint responses and evidenced financial exposure.
Create your Spray Foam Insulation Assessment Report
Answer structured questions about the installation, installer, product, sales process, mortgage or property problem, survey evidence, removal or repair position, finance and financial impact.
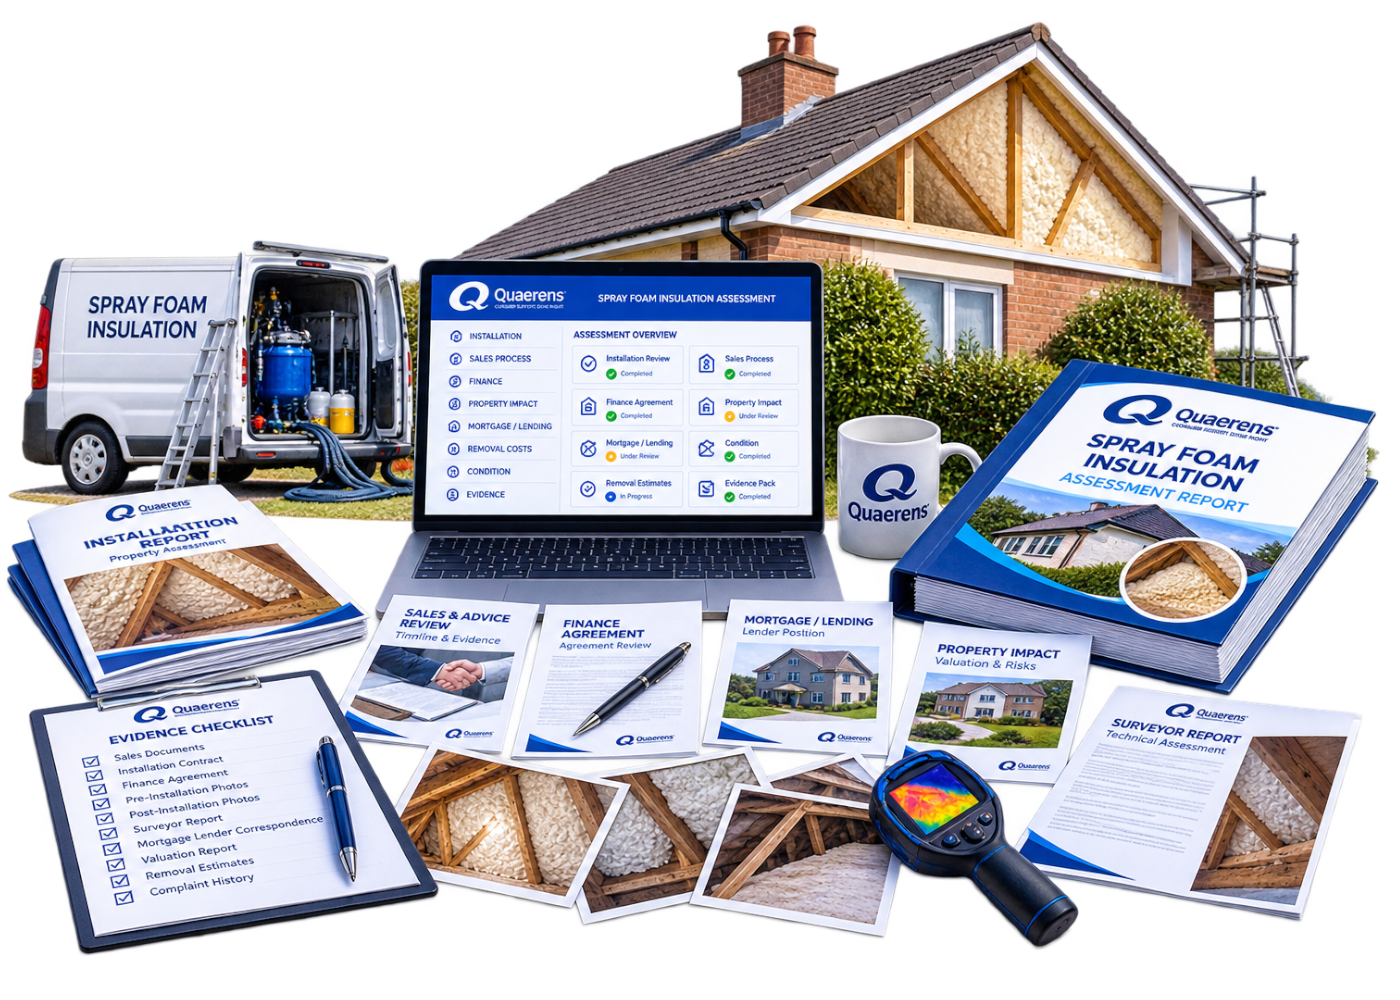
What your report can organise
The report can bring together the property, installation, sales, mortgage, survey, removal, finance and complaint position. The artwork is illustrative and does not show a real client report.
Common Spray Foam problems
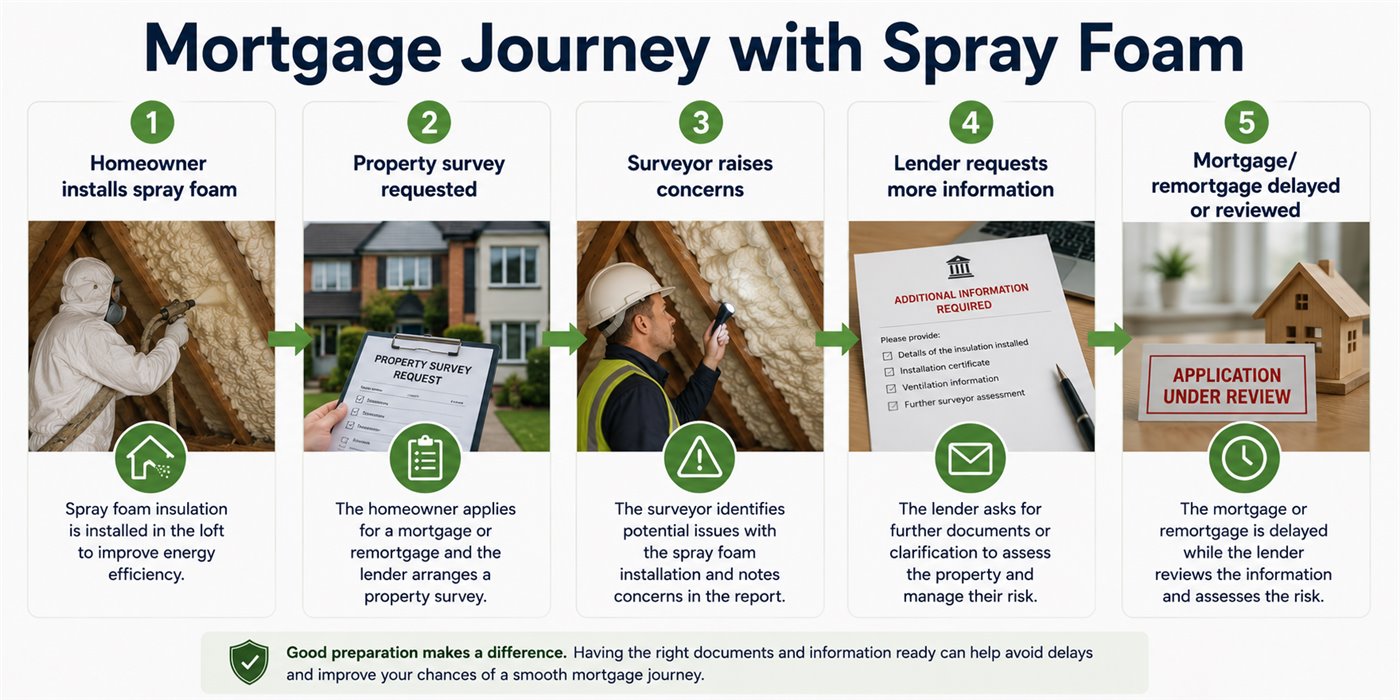
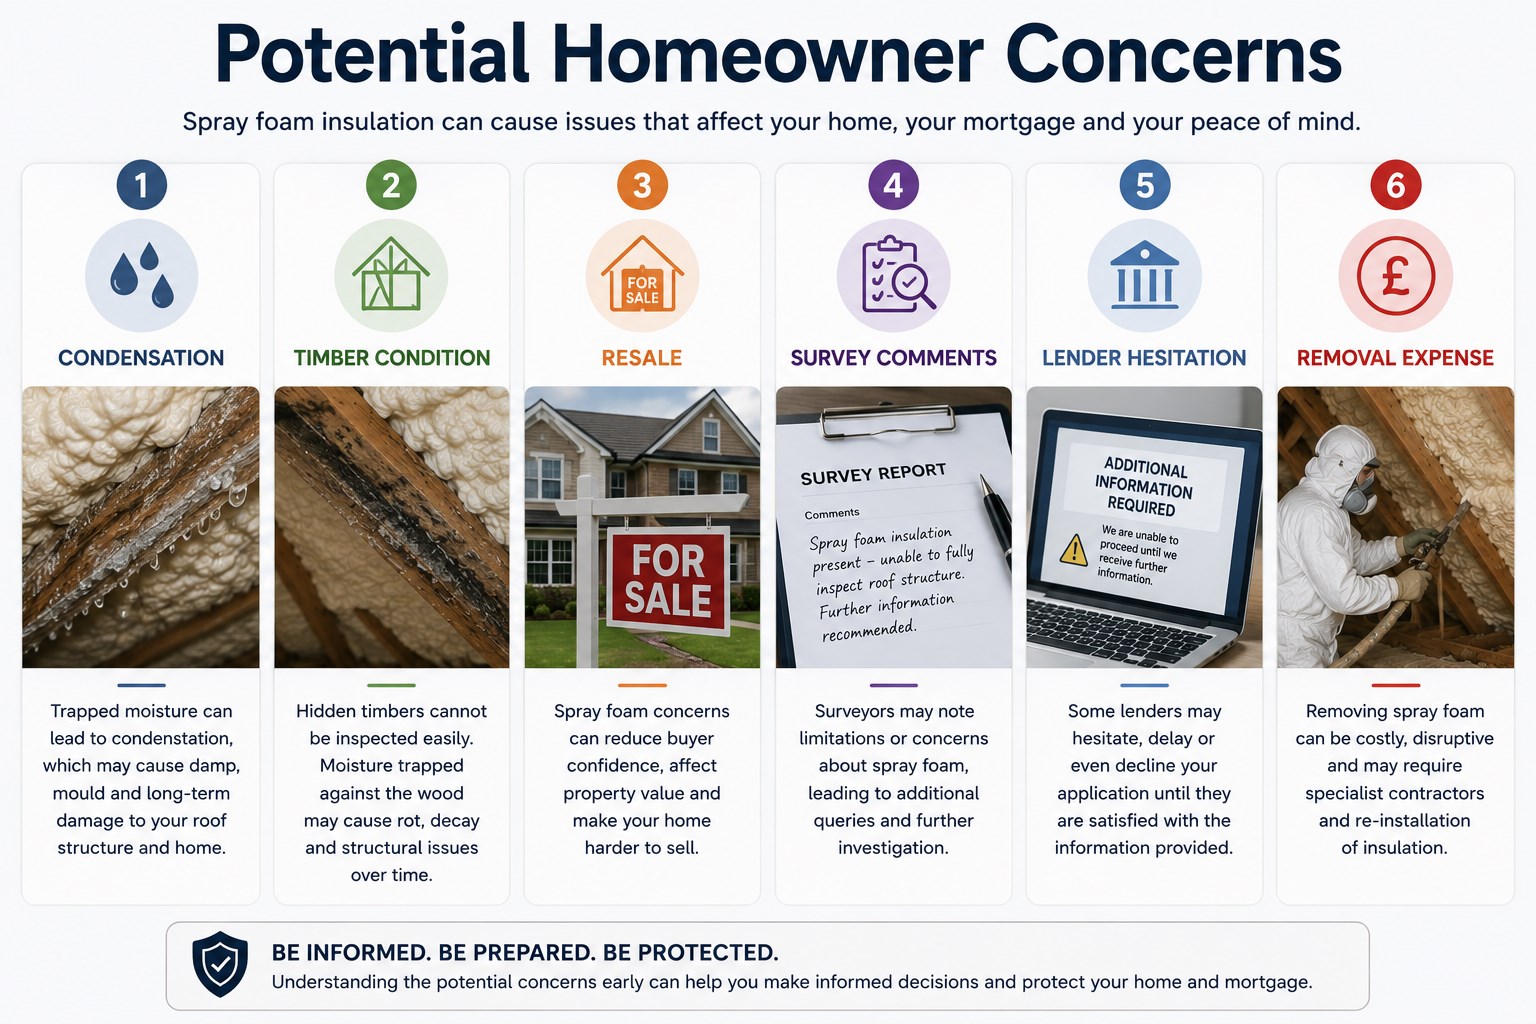
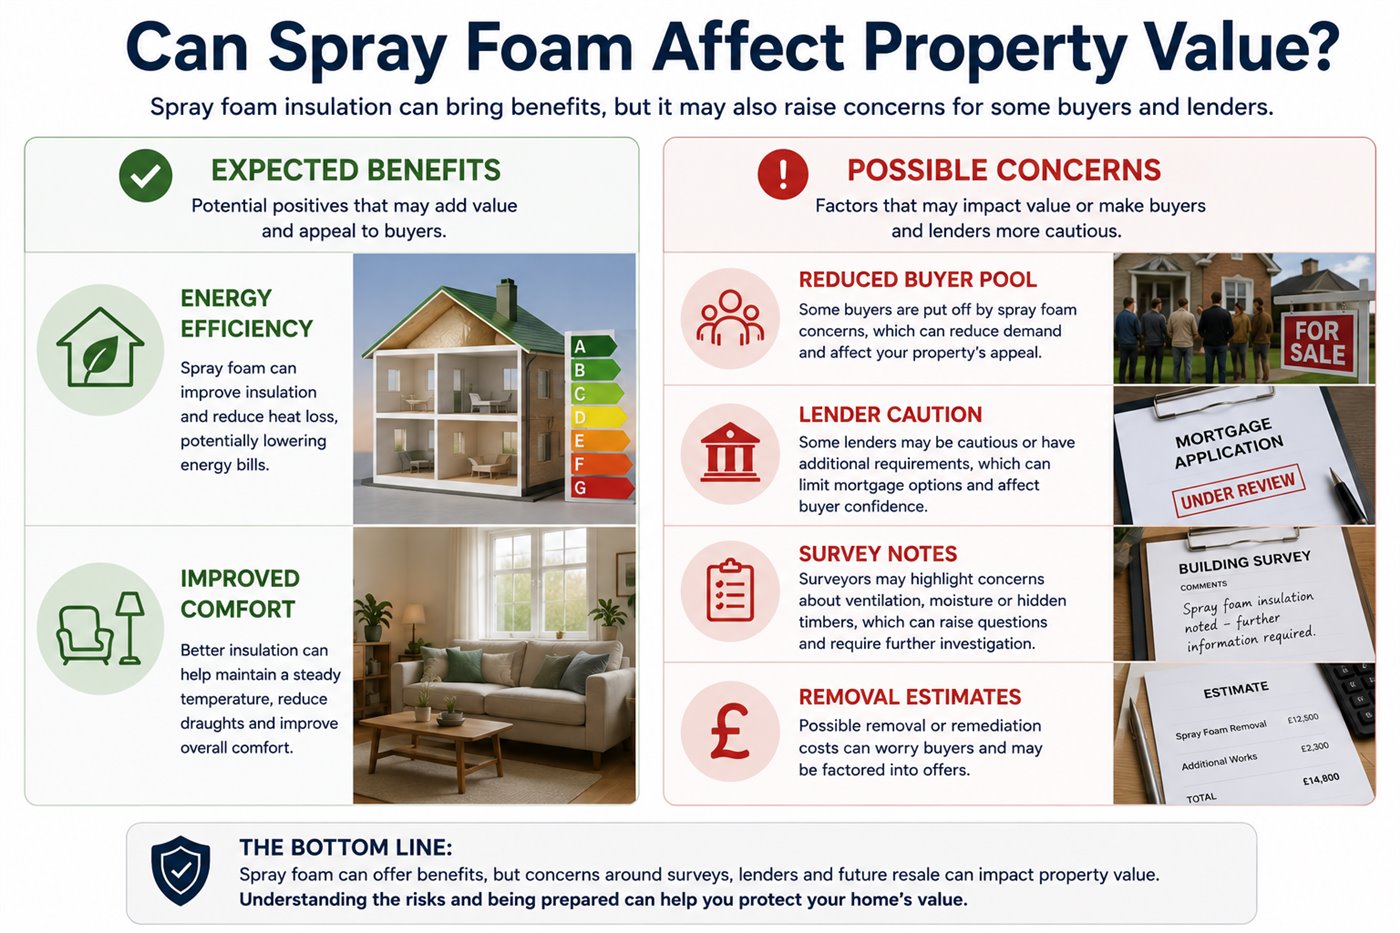
A lender or valuer may request documents, inspection evidence, removal or other conditions. Policies vary and the actual written response matters.
Record the provider, adviser, valuation, written response, requested evidence and whether an alternative arrangement was obtained.
Preserve the offer, survey, buyer and lender correspondence, withdrawal reason and any later sale evidence.
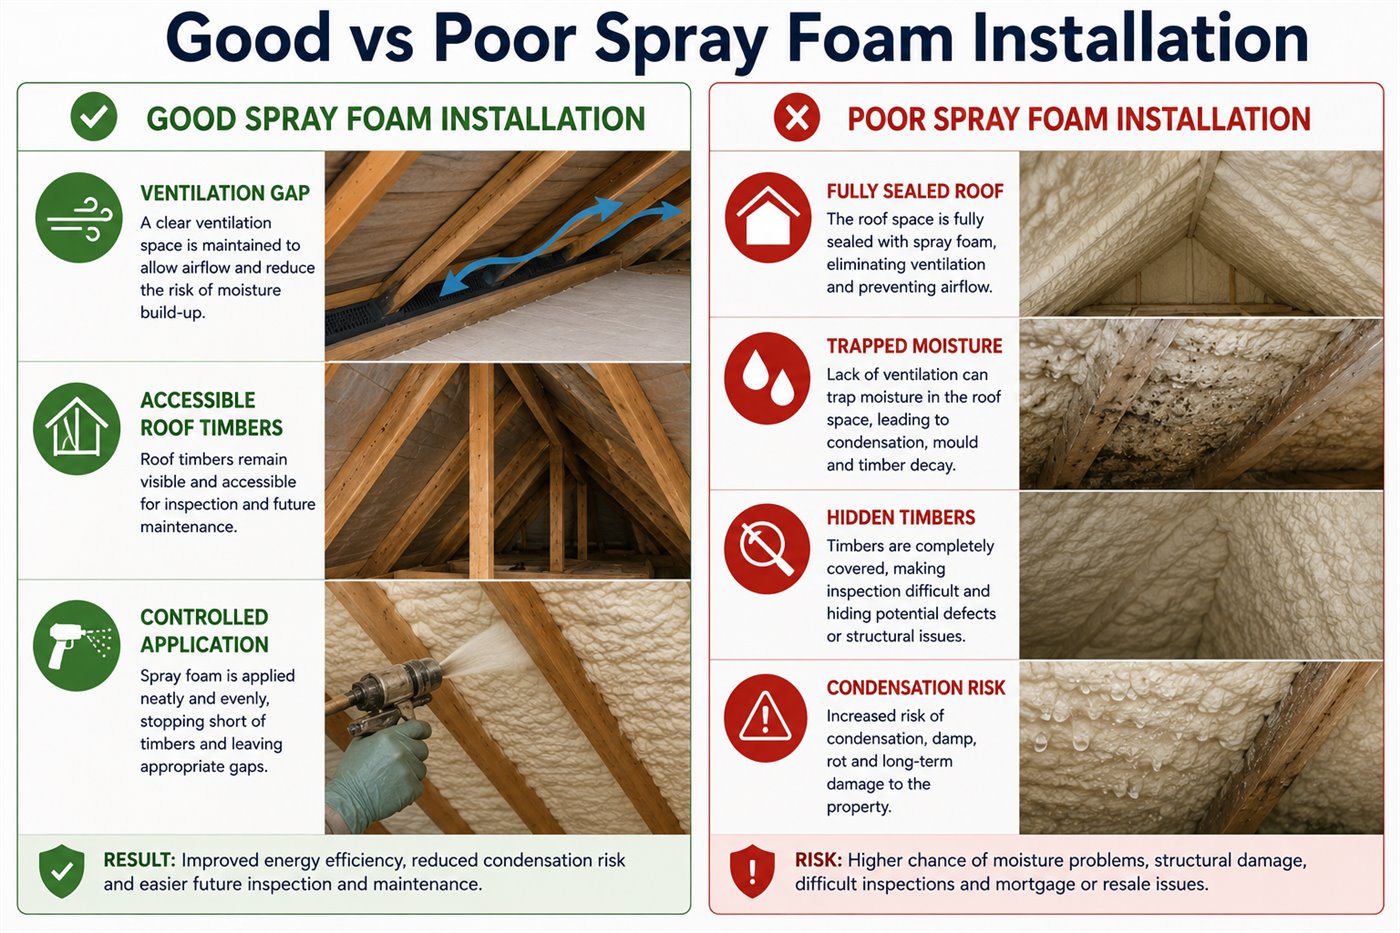
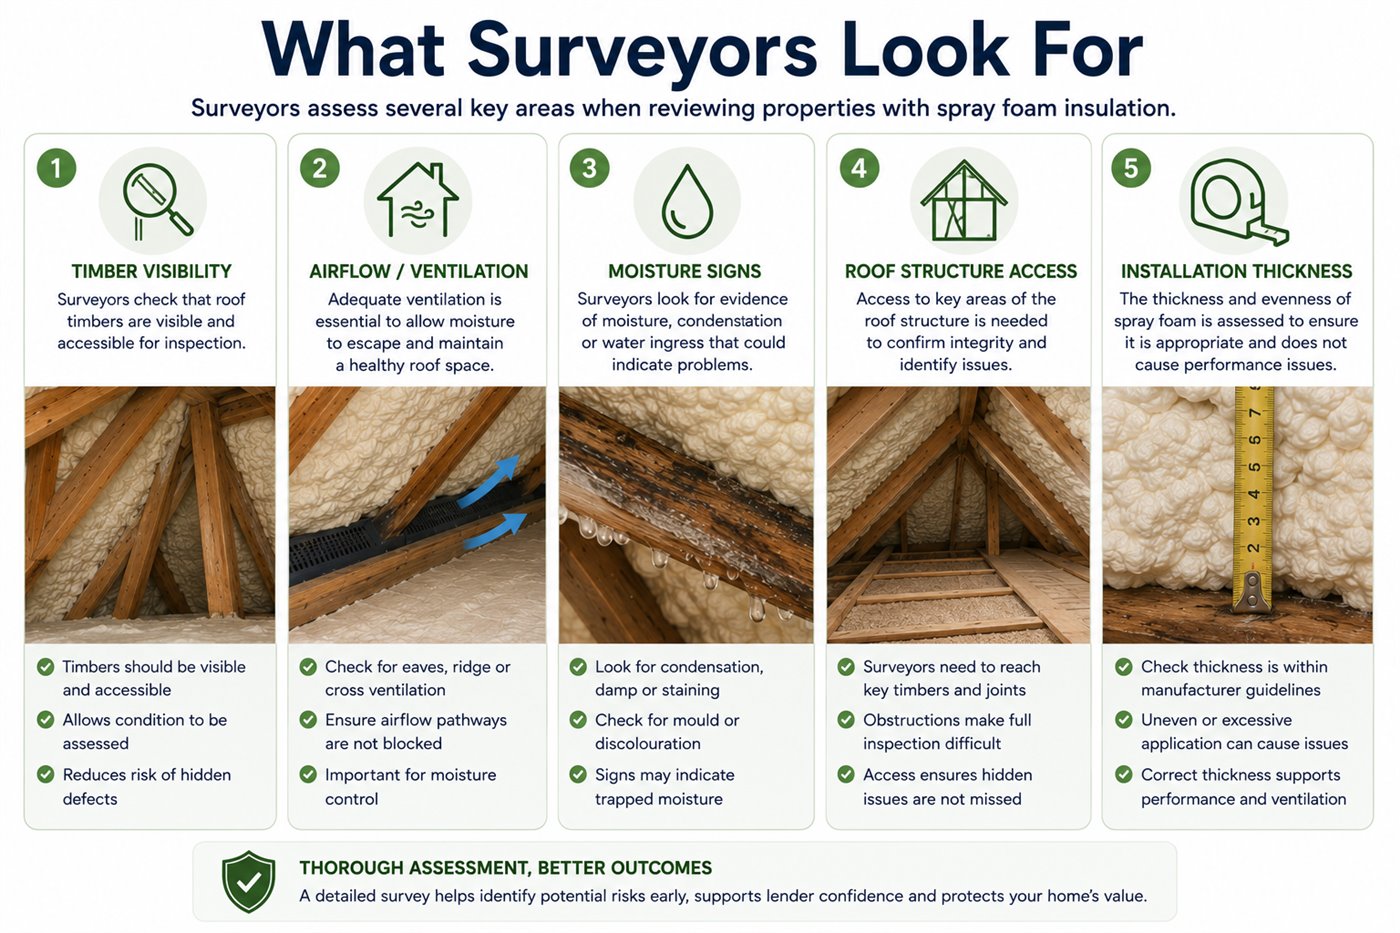
Foam may make parts of the roof harder to inspect, but any conclusion about condition requires appropriate professional evidence.
Record observations separately from professional findings about condensation, moisture, ventilation, damp, mould or rot.
Removal is not automatically necessary. The recommendation, technical reason, scope, cost and reinstatement evidence all matter.
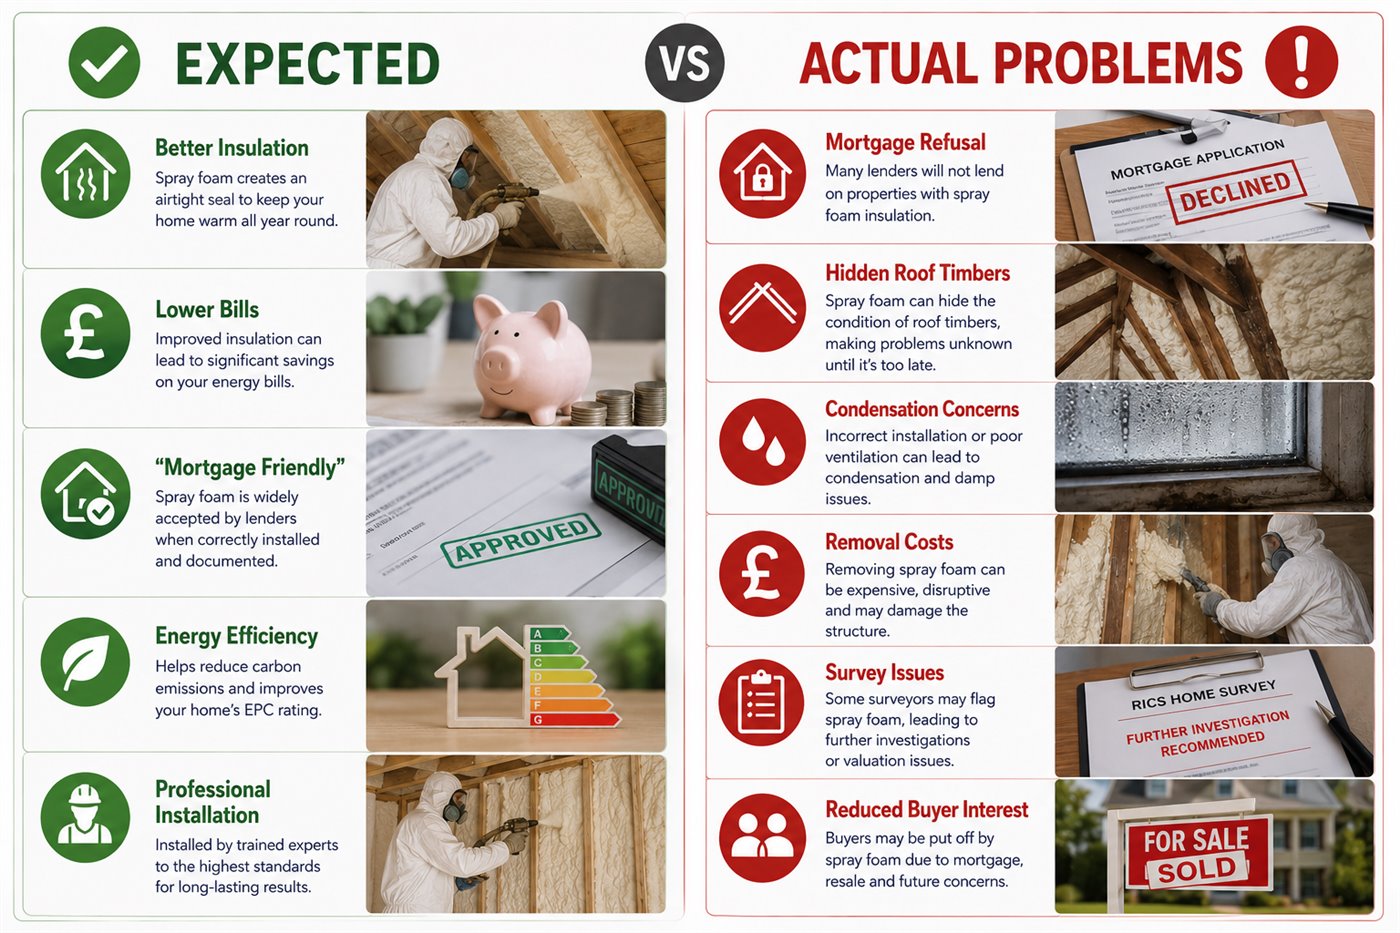
Mortgage, remortgage and equity release
Spray foam does not make every property unmortgageable, and lender policies can change. The strongest evidence is the actual response from the lender, broker, valuer or surveyor in the consumer's case.
Capture the lender, application date, written reason, valuation, conditions, removal or reinspection request and eventual outcome.
Separate comments about inspection access from professional findings about roof condition, timber, moisture or ventilation.
Record later approval, an alternative lender, higher borrowing costs, a delayed sale or a buyer withdrawal without assuming recoverability.
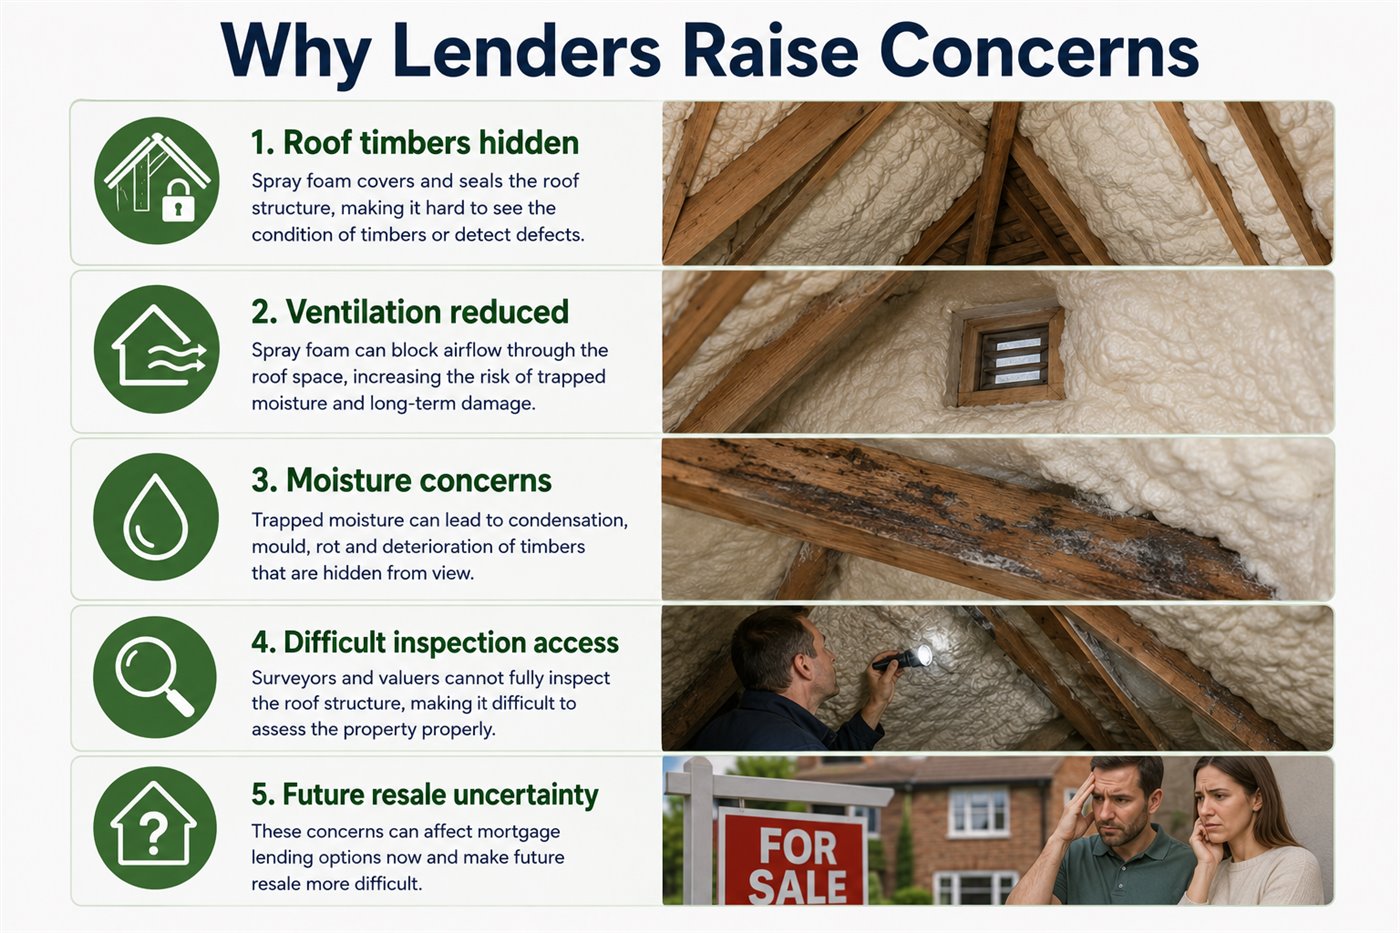
Technical and installation considerations
Open-cell and closed-cell spray foam can differ, but the assessment must also consider location, installation method, ventilation, roof construction, timber visibility, membrane or felt, documentation and current condition. Open-cell foam is not automatically acceptable, and closed-cell foam is not automatically defective.
Certification, including a BBA certificate where genuinely supplied, may be useful evidence. It does not guarantee correct installation, absence of roof issues or mortgage acceptance.
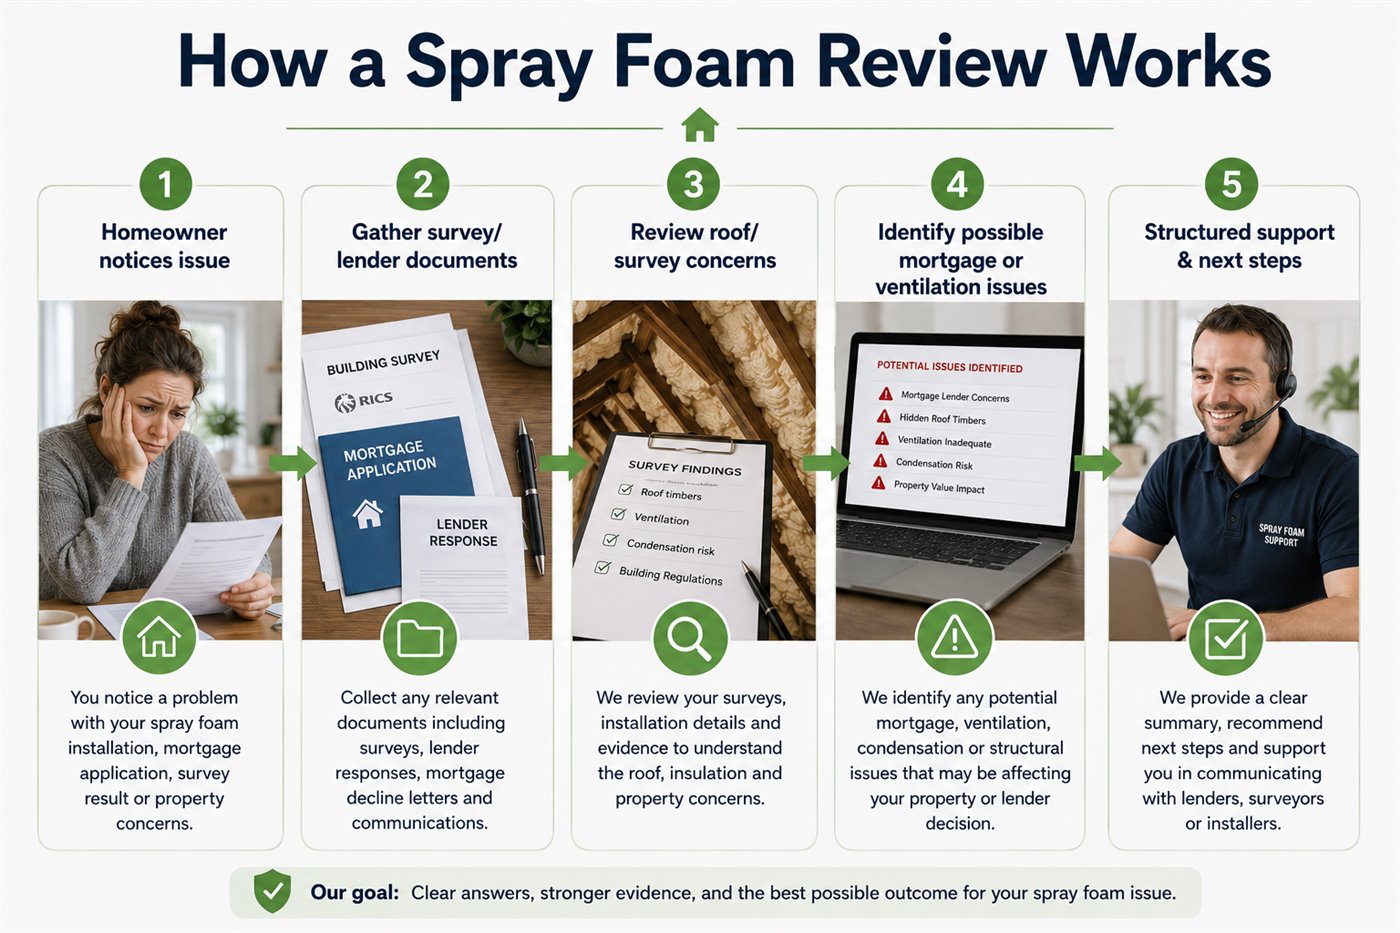
Removal, remediation and roof history
The assessment should record why removal was recommended, who recommended it, the lender or survey requirement, technical evidence, scope, cost, roof impact, reinstatement and any certification after removal.
Keep each contractor, quote, scope, date and outcome separate where a first removal was incomplete or further work followed.
Record who recommended the work, why, the pre-existing roof condition, reports, quotes, paid invoices and evidence of causation.
Preserve photographs, waste-removal records, reinstatement, replacement insulation, completion documents and any later inspection.
Sales, grants, finance and payment
Consumers may report being told that spray foam was mortgage-safe, would increase value, avoid roof replacement, cure damp or was government-backed, approved or grant-funded. The assessment records the exact wording and its source. Consumer recollection remains clearly distinguished from documentary evidence.
Contracts, brochures, emails, messages, salesperson details and installation records may clarify the representations and work performed.
A finance-provider complaint, connected transaction, Section 75 or Financial Ombudsman route may be relevant depending on the agreement, payment structure and evidence.
A warranty provider, guarantee insurer or other responsible party may require separate documents and correspondence, particularly if the installer has ceased trading.
Section 75 does not automatically apply to every financed Spray Foam installation. Spray Foam remains the subject-matter route, with the payment route assessed separately.
What evidence matters?
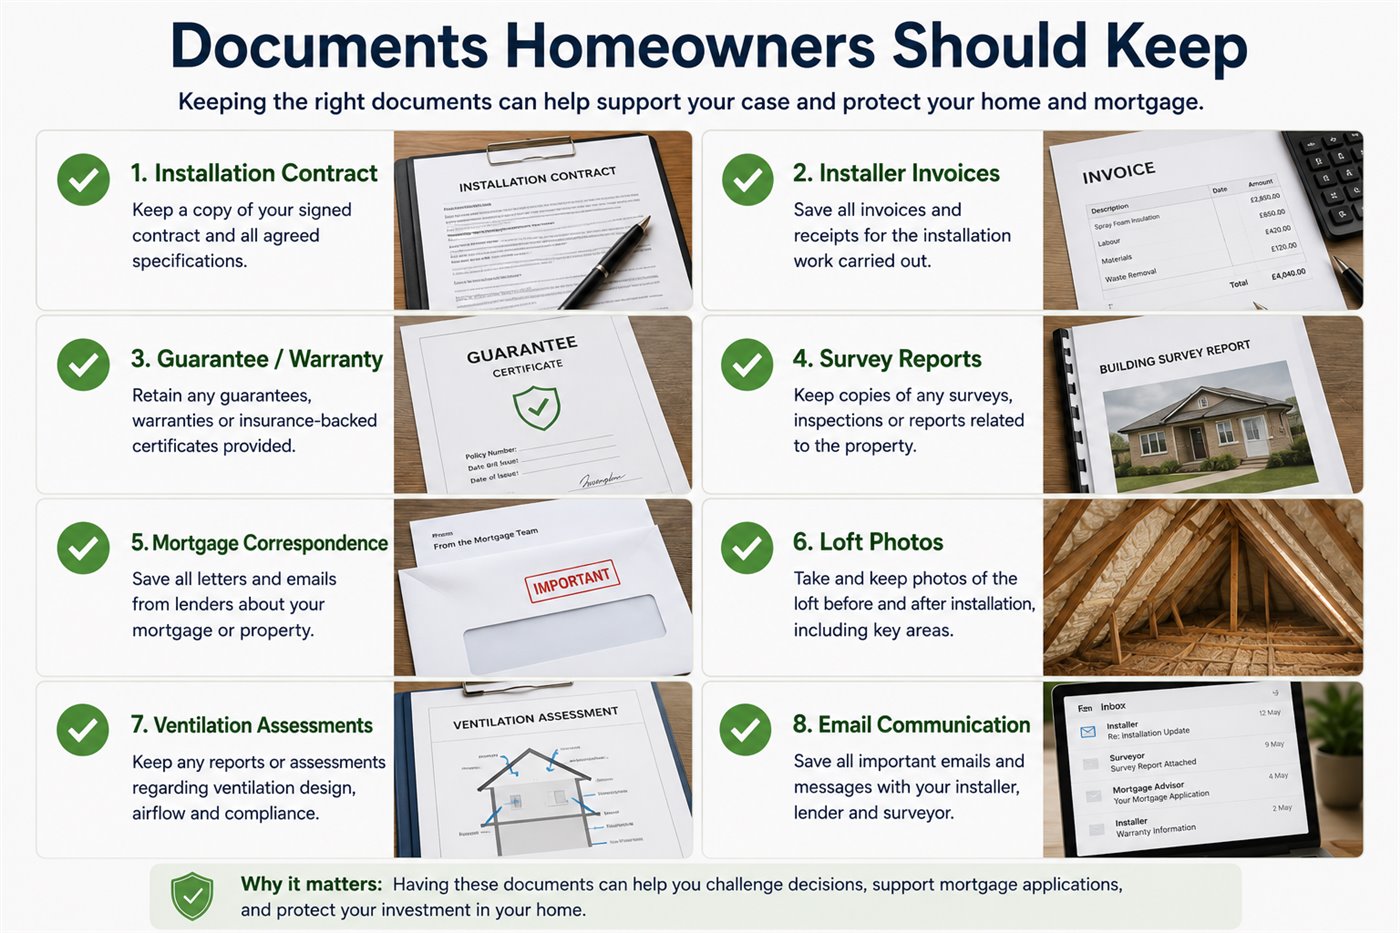
Contract, quote, invoice, order, brochure, emails, messages, grant paperwork, product sheet, guarantee, certification, survey and installation photographs.
Current loft and roof photographs, surveyor or roofer report, moisture or ventilation evidence, valuation and professional findings.
Lender refusal, broker and equity-release correspondence, valuer comments, buyer correspondence, reduced offer and failed-sale chronology.
Removal quotes, scopes, photographs, completion certificate, repair or roof-replacement quote, paid invoices and reinspection.
Finance agreement, pre-contract information, statements, settlement figure, card statements and payment evidence.
Installer, lender, card, warranty or insurer complaint, final responses and ADR or Ombudsman correspondence where relevant.
Chronology and assessment journey
Record the installer, product, property, price and relevant dates.
Add mortgage, value, government, grant, energy, roof and product representations.
Add mortgage, sale, survey, technical, removal or repair events separately.
Identify available contracts, lender responses, reports, photographs, quotes and finance records.
Your information is organised into the professional preliminary Quaerens report format.
Professional findings and financial exposure
Quaerens does not diagnose rot, damp, structural deterioration, trapped moisture, roof failure or the need for full replacement. Consumer observations remain separate from professional findings by a suitably qualified surveyor, roofer or other relevant expert.
Potential components include installation price, finance charges, surveys, valuations, mortgage costs, removal, repeat removal, roof repair, roof replacement, replacement insulation, professional reports and other documented consequential costs.
Figures are classified as documented, client reported, estimated or to be confirmed. Installation price is not added again as finance principal, and quotes are not treated as paid costs. The assessment does not present compensation due or a guaranteed claim value.
Possible responsibility routes
More than one party may be involved. The assessment keeps each company's role, chronology, evidence and financial entries separate without automatically assigning liability.
Sales representations, suitability information, installation work, documentation and complaint handling may require review.
The finance agreement, connected transaction, payment method and complaint evidence determine whether a financial-services route may be relevant.
Guarantee, insurer, removal and roof-work responsibilities must be assessed against each party's own documents and work.
Spray Foam Knowledge Hub
Understand what lender, broker and survey evidence should be organised.
Review provider, valuation and property-document concerns.
Separate inspection limitations, observations and professional findings.
Read about inspection, documentation and property-specific considerations.
Compare scopes, quotes, making good and roof-work evidence.
Understand when a card or connected finance route may warrant consideration.
Frequently asked questions
Prefer to speak to us first?
If you are unsure what documents matter, whether the lender or survey evidence is enough, or whether a Spray Foam Assessment Report is the right next step, the Quaerens intake team can contact you.
Save 020 8050 0725 as Quaerens so you recognise our call, or message us through the live chat.
Quaerens focuses first on establishing the facts and preparing the evidence.
Where legal advice or representation becomes appropriate, eligible matters may be referred to our solicitor partner, GSP Law, an independent SRA-regulated firm.
Meet Our Solicitor Partner